Tuesdays are all about academic (and practitioner) literature at Abnormal Returns. You can check out last week’s links including a look at ESG analytics.
online pharmacy order tadapox without prescription with best prices today in the USA
Quote of the Day
"Asset management risk management seems to focus on the mapping of risk into a return-volatility or VaR framework and spends less time on the process."
(Mark Rzepczynski)
Chart of the Day
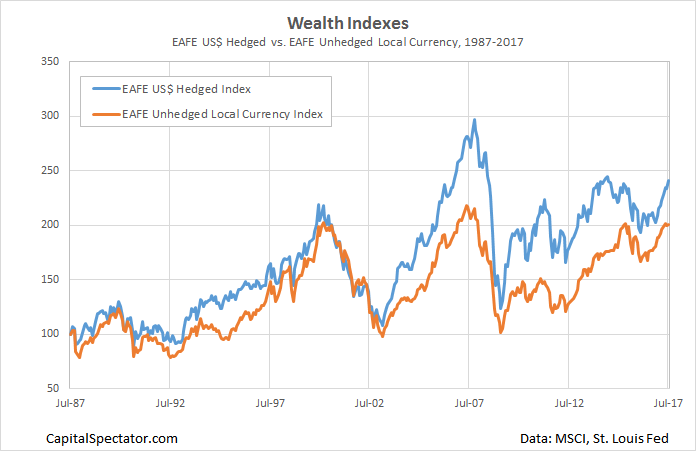
“The implication: foreign equity investing offers a bigger diversification bang for the buck by forgoing currency hedging.”
Bonds
- How the Fed's balance sheet affects the term premium. (papers.ssrn.com)
- Can bond portfolio returns be 'factorized'? (blog.alphaarchitect.com)
Corporate finance
- In what geographies are CEOs more willing to fudge the numbers? (wsj.com)
- PE-backed firms doubled down during the financial crisis. (papers.ssrn.com)
Momentum
- On the diversification benefits of time-series momentum. (blog.alphaarchitect.com)
- Why is absolute momentum on the no-go list for most managers? (dualmomentum.net)
Research
- Testing some US return anomalies overseas shows promise. (papers.ssrn.com)
- Who much money is in volatility-targeted strategies and should we be concerned? (mrzepczynski.blogspot.com)
- How investors should think about investing in quant strategies. (aqr.com)
- Why fund portfolios have become more liquid over time. (papers.ssrn.com)