Tuesdays are all about academic (and practitioner) literature at Abnormal Returns. You can check out last week’s edition including a look at the global market portfolio.
Quote of the Day
"Since poker teaches that you will make the right decision and still lose money, it trains you to emotionally decouple decision quality from result quality."
(Kris Abdelmessih)
Chart of the Day
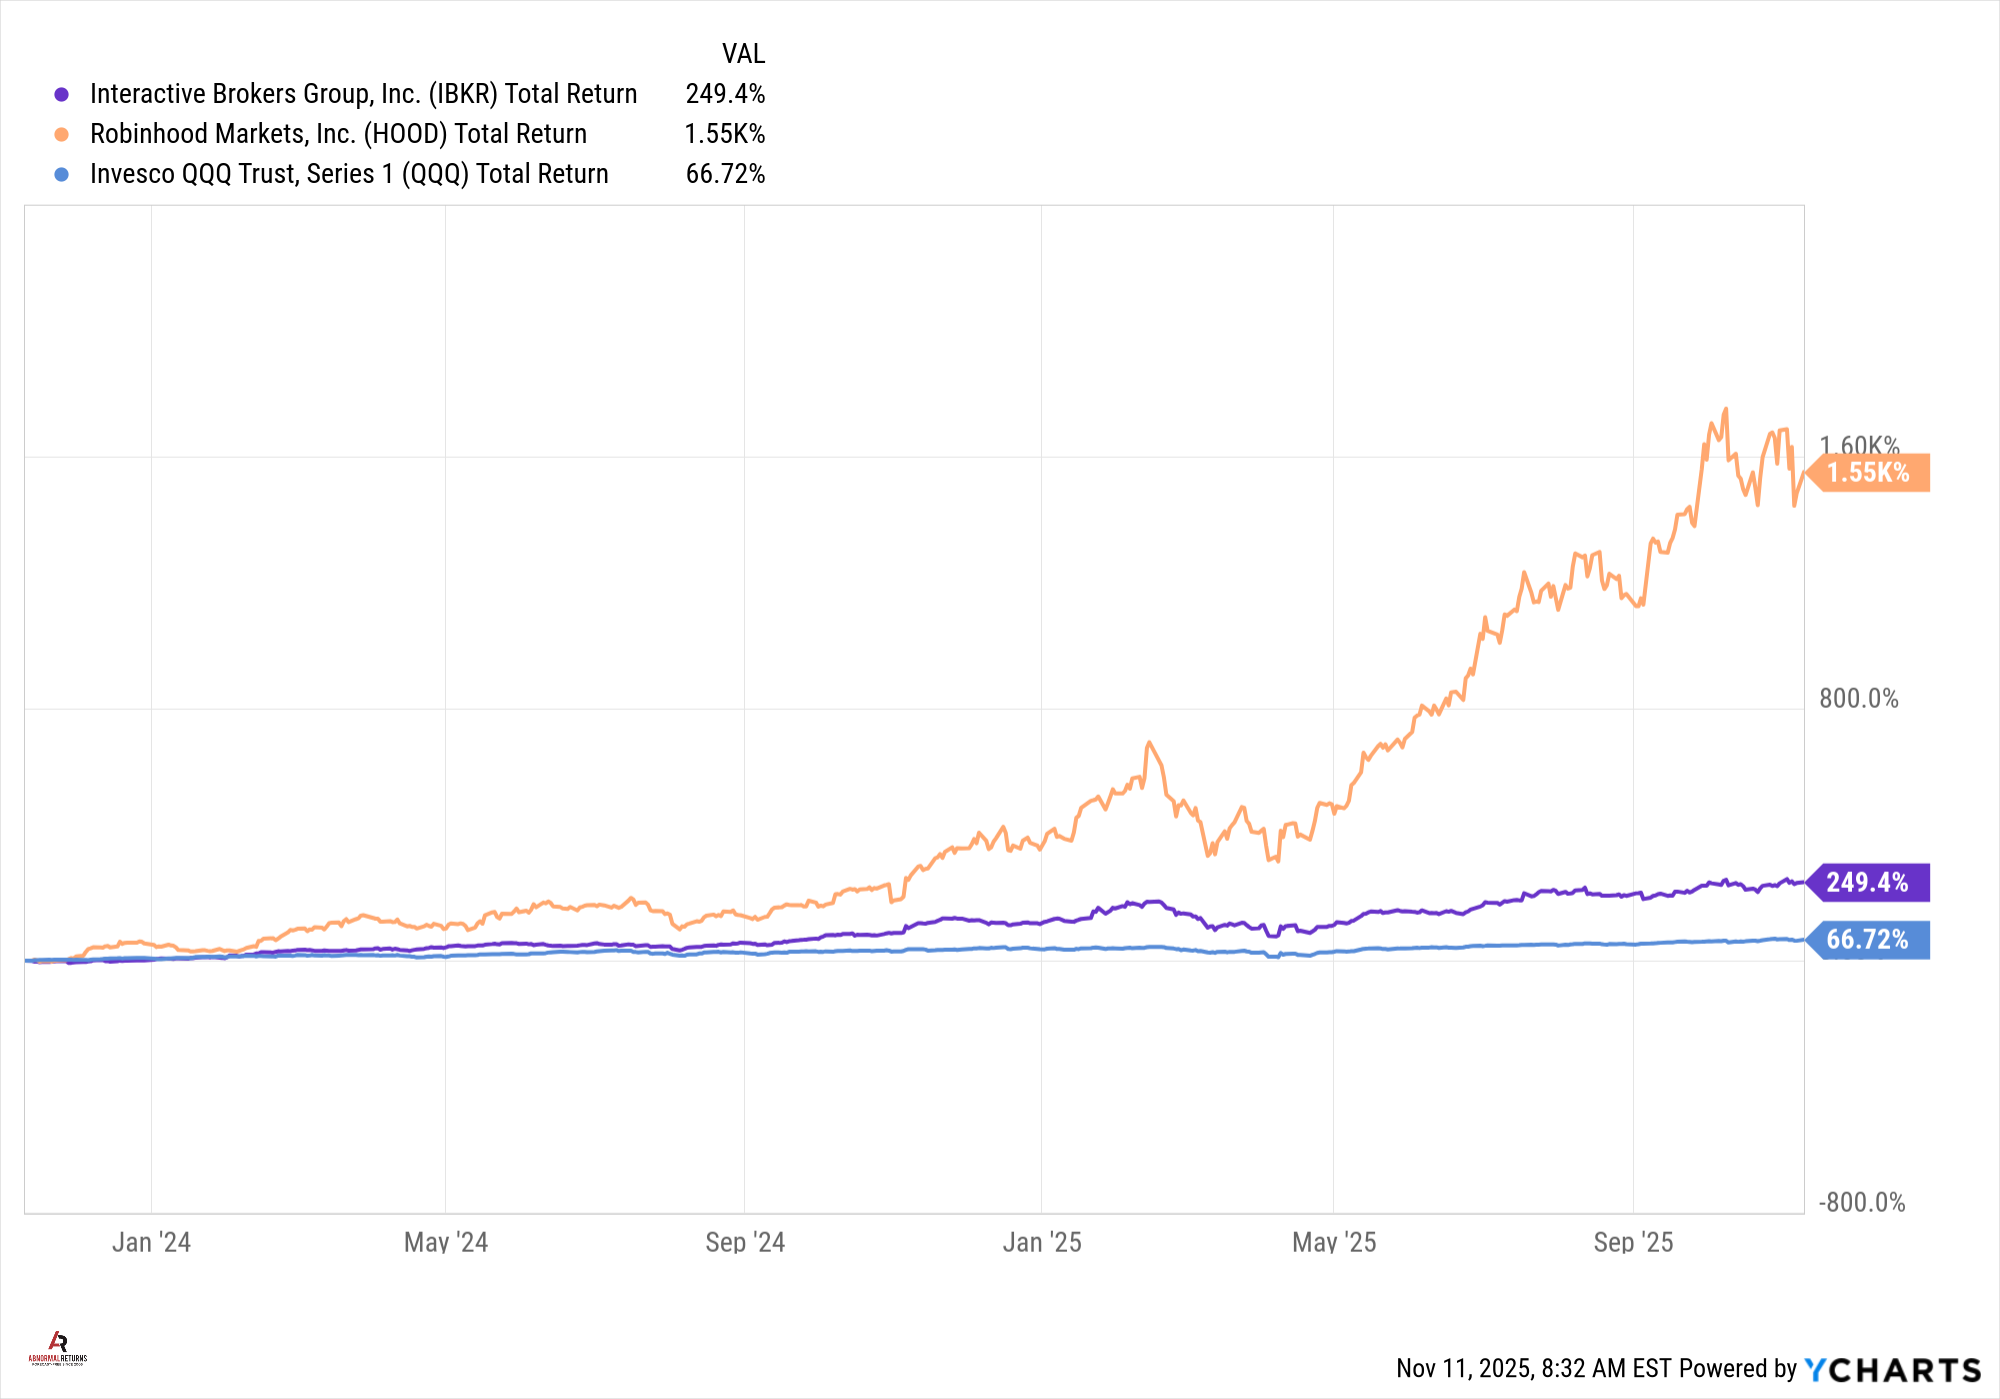
Owen Lamont, “So, in summary, many past bubbles have seen surging broker share prices, peaking either prior to or concurrent with the bubble.” (chart via YCharts)
Quant stuff
- A round-up of recent academic research papers including 'Momentum Factor or Factor Momentum in REIT Market?' (alphainacademia.substack.com)
- Asset managers need to decide what AI is good for, and what it is not. (blogs.cfainstitute.org)
- What trading floors tell us about the evolution of markets. (rupakghose.substack.com)
- How the big credit ratings agencies compare. (on.ft.com)
Research
- Robin J. Brooks, "The basis trade is just a carry trade, except that it involves Treasuries and Treasury futures. Its worst enemy is volatility and unpredictability..." (robinjbrooks.substack.com)
- A class of Japanese companies are cheap - how to capture a re-rating. (mailchi.mp)
- Capital allocation may be company management's biggest responsibility. (morganstanley.com)
- Position sizing matters more than you think. (excessreturnspod.substack.com)
- There's no debate when it comes to the tax efficiency of ETFs vs. mutual funds. (alphaarchitect.com)
- Why measuring the returns for private equity and credit funds is a challenge. (institutionalinvestor.com)
- How to take advantage of systematic investor biases. (papers.ssrn.com)
- Putting the move in gold into some perspective. (aswathdamodaran.blogspot.com)
- Liquidity as an investment factor. (rockandturner.substack.com)